Week Ending September 11, 2026
Weekly Storage and S/D Brief - Week Ending 10/16/2026
Week Ending October 16, 2026
SynMax Analytics | Published October 21, 2026
Headline
SynMax models a +88 Bcf injection for the week ending October 16, up 21 Bcf from the prior week's EIA-reported +67 Bcf build. If confirmed, working gas storage would stand at 3,655 Bcf. That is 143 Bcf below last year's pace (3,798 Bcf) but 48 Bcf above the five-year average.
Review the full analysis on the dashboard.
Storage Summary
Last week's injection was set by reduced supply. This week's re-acceleration comes mostly from demand: total demand fell 1.68 Bcf/d WoW to 104.53 Bcf/d as CONUS power burn dropped 3.12 Bcf/d to 34.39 Bcf/d, its steepest weekly decline of the autumn. Supply also recovered, with total gross supply up 0.88 Bcf/d to 117.29 Bcf/d. Dry gas production rose 0.42 Bcf/d to 109.73 Bcf/d and Canadian pipeline imports firmed 0.46 Bcf/d to 7.56 Bcf/d. A 1.54 Bcf/d rebound in LNG feedgas to 19.82 Bcf/d was the main offset.
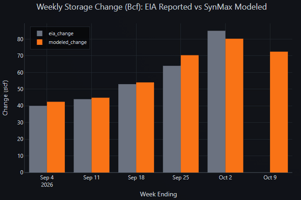
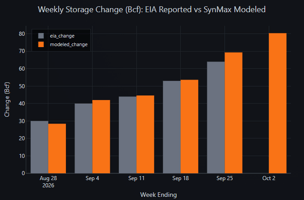
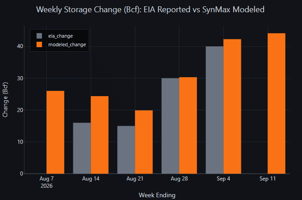
Model accuracy: Across the full scored window since July 3 (fifteen weeks, CONUS), the SynMax storage-number model has averaged a mean absolute error (MAE) of 3.5 Bcf, with a small positive (over-injection) bias of +0.4 Bcf and a 0.97 correlation with EIA-reported changes. Over the last five weeks the MAE was 2.8 Bcf (bias +0.3 Bcf).
| Week Ending | EIA (Bcf) | SynMax Model (Bcf) | Error |
|---|---|---|---|
| Sep 11 | +44 | +44.3 | +0.3 |
| Sep 18 | +53 | +53.0 | 0.0 |
| Sep 25 | +64 | +68.0 | +4.0 |
| Oct 02 | +85 | +78.9 | -6.1 |
| Oct 09 | +67 | +70.5 | +3.5 |
The accuracy table reflects SynMax's latest supply/demand models. Modeled weekly values are recalculated as source data updates, so the resulting weekly storage may differ modestly from the official weekly storage-number call scored directly against EIA releases.
Primary Driver: Power Burn Slides as Supply Recovers
CONUS electric power burn fell 3.12 Bcf/d WoW to 34.39 Bcf/d. Almost three-quarters of the drop came from the South Central region, where power burn fell 2.31 Bcf/d to 10.22 Bcf/d. The decline was concentrated in the Gulf, consistent with lingering demand effects after Hurricane Isaias. The West also contributed as a cool spell moved into the Pacific (-0.95 Bcf/d) and Mountain (-0.51 Bcf/d) regions. Higher wind generation was also a contributing factor.
On the supply side, the storm-related losses from the prior week reversed. Combined South Central and Gulf production recovered 0.34 Bcf/d to 44.13 Bcf/d and West production added 0.36 Bcf/d to 20.88 Bcf/d. Northeast production slipped a further 0.23 Bcf/d to 33.67 Bcf/d and remains about 1.4 Bcf/d below last year. Canadian pipeline imports rebounded 0.46 Bcf/d to 7.56 Bcf/d, recovering about half of the prior week's decline.
Res/Com demand rose only 0.27 Bcf/d to 10.83 Bcf/d, and industrial demand was essentially flat at 22.42 Bcf/d. Net, the daily surplus widened 2.52 Bcf/d to 12.59 Bcf/d, lifting the modeled injection to +88.1 Bcf from the +70.5 Bcf model value for the prior week (+67 Bcf EIA-reported).
Weather Context
National population-weighted CDDs averaged 4.5 for the week ending October 16, down from 5.3 the prior week but still above the year-ago 2.4:
- Heating degree days rose modestly to 3.6 from 3.2, but stayed well below the year-ago level of 6.0. Res/Com demand of 10.83 Bcf/d ran 1.93 Bcf/d below last year's 12.76 Bcf/d.
- Weather split along an east-west line. The Pacific (HDD 5.5) and Mountain (HDD 8.9) regions turned sharply cooler, while the East warmed (HDD 2.8 vs 4.9) and South Central stayed warm (CDD 10.6).
- That split blunted the heating response. The regions that cooled are small heating markets, while the large East heating market warmed, so national Res/Com demand barely moved despite the higher national HDD count.
Supply & Demand Factor Changes (WoW)
| Factor | WE 10/09 (Bcf/d) | WE 10/16 (Bcf/d) | Δ WoW | Impact |
|---|---|---|---|---|
| SUPPLY | ||||
| Dry Gas Production | 109.30 | 109.73 | +0.42 | Bearish |
| Canada Pipeline Imports | 7.11 | 7.56 | +0.46 | Bearish |
| Total Gross Supply | 116.41 | 117.29 | +0.88 | Bearish |
| DEMAND | ||||
| Electric Power | 37.50 | 34.39 | -3.12 | Bearish |
| Industrial | 22.50 | 22.42 | -0.09 | Bearish |
| Res/Com | 10.56 | 10.83 | +0.27 | Bullish |
| LNG Feedgas (exports) | 18.28 | 19.82 | +1.54 | Bullish |
| Mexico Pipeline Exports | 7.03 | 6.78 | -0.25 | Bearish |
| Canada Pipeline Exports | 2.35 | 2.41 | +0.06 | Bullish |
| Lease/Plant/Pipe/Vehicle | 8.01 | 7.90 | -0.11 | Bearish |
| Total Demand | 106.21 | 104.53 | -1.68 | Bearish |
| Balancing Factor | +0.14 | +0.17 | +0.03 | — |
| Implied Daily Surplus | 10.07 | 12.59 | +2.52 | |
| Weekly Injection (Bcf) | +70.5 | +88.1 | +17.6 |
Note: Canadian pipeline imports are treated as a supply source; Canadian pipeline exports are treated as demand (gas leaving the domestic market). The Balancing Factor captures the residual between independently modeled supply and demand components and is reported below the totals. It is folded into the implied change but excluded from Total Supply and Total Demand. Prior-week values reflect the latest model run and may differ slightly from last week's brief.
Secondary Factors
LNG Feedgas: Broad Recovery Lifts Exports
Total LNG feedgas rose 1.54 Bcf/d to 19.82 Bcf/d. This was the largest bullish (tightening) move on the week and the main offset to the power-burn decline. Freeport recovered 0.68 Bcf/d to 2.15 Bcf/d after last week's outage, and Cove Point returned from maintenance on October 12 at 0.8 Bcf/d (0.58 Bcf/d avearge for the week). Golden Pass added 0.18 Bcf/d to 0.56 Bcf/d as its ramp continued, and the terminal reached a new daily high of 0.82 Bcf/d on October 21. Sabine Pass (4.70), Plaquemines (4.03) and Corpus Christi (3.56) held steady near full utilization. Feedgas is now running 1.76 Bcf/d above the year-ago 18.06 Bcf/d.
Res/Com, Mexico Exports & Industrial
Res/Com demand edged up 0.27 Bcf/d to 10.83 Bcf/d. The east-west weather split kept early-season heating load in check, and Res/Com remained well below last year's level for the same week. Pipeline exports to Mexico eased 0.25 Bcf/d to 6.78 Bcf/d, and industrial demand was flat at 22.42 Bcf/d. Together these factors were modestly bearish. The power-burn decline and the supply recovery outweighed the LNG rebound.
Regional Power Burn
| Region | WE 10/09 (Bcf/d) | WE 10/16 (Bcf/d) | Δ WoW | LY (Bcf/d) | YoY Δ |
|---|---|---|---|---|---|
| East | 14.16 | 14.52 | +0.36 | 13.90 | +0.62 |
| Midwest | 4.17 | 4.46 | +0.30 | 3.96 | +0.51 |
| South Central | 12.53 | 10.22 | -2.31 | 10.37 | -0.15 |
| Mountain | 3.23 | 2.72 | -0.51 | 2.66 | +0.06 |
| Pacific | 3.41 | 2.46 | -0.95 | 1.98 | +0.47 |
| CONUS | 37.50 | 34.39 | -3.12 | 32.88 | +1.51 |
Power burn reversed last week's pattern. The South Central (-2.31) and the West (Pacific -0.95, Mountain -0.51) shed load, while the East (+0.36) and Midwest (+0.30) edged higher on warmer late-season weather. South Central burn has now slipped slightly below year-ago levels for the first time in several weeks. Nationally, CONUS power burn still runs 1.51 Bcf/d above last year.
Outlook: Week Ending October 23
Early data for the week ending October 23 (five of seven days, through October 21) point to another large build of +79 Bcf. Heating demand has arrived in earnest, but sharply lower power burn and higher supply are offsetting it.
- Heating load arrives: CONUS HDDs jumped above 10 over the October 17-18 weekend, the first real cold of the season. Res/Com demand has climbed to about 16.0 Bcf/d so far this week, more than 5 Bcf/d above the week ending October 16.
- Power burn collapses: Power burn is averaging about 29.3 Bcf/d week-to-date, down roughly 5 Bcf/d, as cooler weather removes most of the remaining cooling load. This largely cancels the Res/Com gain.
- Supply firm: Dry gas production is averaging about 111.0 Bcf/d week-to-date (+1.3 Bcf/d), with Gulf volumes fully restored.
- LNG feedgas near 20.5 Bcf/d: Throughput remains firm, supported by the Freeport and Cove Point recoveries and continued gains at Golden Pass.
Early read: ~+79 Bcf based on week-to-date fundamentals.
Methodology & Data Sources
Storage change is modeled as Total Supply (Dry Gas Production + Canadian Pipeline Imports + LNG Imports) minus Total Demand (all consumption sectors + LNG feedgas exports + pipeline exports), net of the Balancing Factor calibration residual, multiplied by seven days. The EIA storage week runs Saturday through Friday; the week ending October 16 covers Saturday, October 10 through Friday, October 16. Canadian pipeline imports are treated as a supply source supplementing domestic production, and Canadian pipeline exports are treated as demand. The Balancing Factor (+0.17 Bcf/d this week) is the residual between independently modeled supply and demand components and calibrates the injection estimate against EIA actuals.
Data sources: SynMax daily production model (hdl.daily_production), SynMax demand model (hdl.gas_demand, baseline scenarios), SynMax LNG feedgas model (hdl.lng_feed_gas), EIA Weekly Natural Gas Storage Report (hdl.eia_storage_final), NOAA GFS/HRRR weather data.
Disclaimer: This report is produced by SynMax Analytics for informational purposes only. Modeled figures are estimates and may differ from official EIA releases. Past model accuracy does not guarantee future performance.