Week Ending August 28, 2026
Weekly Storage and S/D Brief - Week Ending 10/2/2026
Week Ending October 2, 2026
SynMax Analytics | Published October 7, 2026
Headline
SynMax models an 80 Bcf injection for the week ending October 2, up 16 Bcf from the prior week's EIA-reported 64 Bcf build and the largest weekly build since June. If confirmed, working gas storage would stand at 3,495 Bcf, 136 Bcf below last year and 75 Bcf (+2.2%) above the five-year average.
Review the full analysis on the dashboard.
For a list of SynMax's other standard dashboards, click here.
Storage Summary
This week’s modeled 80 Bcf injection marks the sixth consecutive week of increasing injections, driven by the continued fade of cooling demand as the calendar turns into October and the shoulder-season lull deepens. Total demand fell 3.12 Bcf/d WoW to 106.17 Bcf/d, driven by power burn declining 2.13 Bcf/d to 38.20 Bcf/d as cooling demand continues to wane. Supply eased only marginally (-0.28 Bcf/d to 118.22 Bcf/d) as dry gas production slipped -0.79 Bcf/d to 110.25 Bcf/d, partially offset by a +0.51 Bcf/d rebound in Canadian pipeline imports to 7.97 Bcf/d.
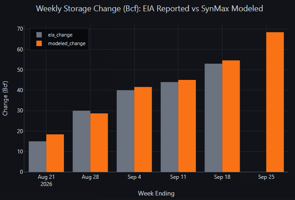
Model accuracy: Over the past 5 storage weeks, the SynMax storage-number model has averaged a mean absolute error (MAE) of 1.7 Bcf (bias +1.7 Bcf).
| Week Ending | EIA (Bcf) | SynMax Model (Bcf) | Error |
|---|---|---|---|
| Aug 28 | +30 | +30.2 | +0.2 |
| Sep 04 | +40 | +41.6 | +1.6 |
| Sep 11 | +44 | +44.6 | +0.6 |
| Sep 18 | +53 | +53.6 | +0.6 |
| Sep 25 | +64 | +69.3 | +5.3 |
The accuracy table reflects the current SynMax supply and demand models and may differ modestly from the official weekly storage-number call scored directly against EIA releases.
Primary Driver: Cooling Demand Declines
The defining feature of the week ending October 2 was the continued, orderly retreat in cooling demand as autumn took firm hold. Total demand fell -3.12 Bcf/d WoW to 106.17 Bcf/d, led by a -2.13 Bcf/d decline in CONUS electric power burn to 38.20 Bcf/d. National population-weighted CDDs eased to 5.3 from 6.1 the prior week, essentially matching the year-ago 5.3 and leaving cooling load with little further room to fall.
The cooldown was concentrated in the South Central this week with burns there falling 1.34 Bcf/d to 12.66 as lingering Texas and Gulf Coast heat finally relaxed. Smaller declines were observed in the East (-0.44 to 15.06), Midwest (-0.25 to 4.75) and Mountain (-0.22 to 3.03) regions. The Pacific was the lone gainer (+0.12 Bcf/d to 2.70). Nationally, power burn drifted back to roughly flat to last year’s levels at 37.98 Bcf/d (+0.22 Bcf/d YoY), after dipping below last year the prior week.
On the supply side, dry gas production eased a modest -0.79 Bcf/d to 110.25 Bcf/d, continuing to drift off its summer high, although the pullback was nearly fully cushioned by a +0.51 Bcf/d rebound in Canadian pipeline imports to 7.97 Bcf/d.
Weather Context
National population-weighted CDDs averaged 5.3 for the week ending October 2, down from 6.1 the prior week and essentially even with the year-ago 5.3:
- National cooling demand continued to fade as the calendar turned into October, pulling the national CDD count toward its seasonal floor
- The retreat was led by the South Central this week as the last of the Gulf Coast heat broke, while the northern regions were already near their autumn baseline
- Heating degree days ticked up to 2.3 (vs 1.5 year-ago), a first hint of early-season heating load stirring across the northern tier, though not yet enough to meaningfully offset the loss of cooling demand
Supply & Demand Factor Changes (WoW)
| Factor | WE 9/25 (Bcf/d) | WE 10/02 (Bcf/d) | Δ WoW | Impact |
|---|---|---|---|---|
| SUPPLY | ||||
| Dry Gas Production | 111.05 | 110.25 | -0.79 | Bullish |
| Canada Pipeline Imports | 7.45 | 7.97 | +0.51 | Bearish |
| Total Gross Supply | 118.50 | 118.22 | -0.28 | Bullish |
| DEMAND | ||||
| Electric Power | 40.33 | 38.20 | -2.13 | Bearish |
| Industrial | 22.31 | 22.27 | -0.04 | Bearish |
| Res/Com | 9.86 | 9.54 | -0.31 | Bearish |
| LNG Feedgas (exports) | 18.69 | 18.60 | -0.09 | Bearish |
| Mexico Pipeline Exports | 7.31 | 6.98 | -0.34 | Bearish |
| Canada Pipeline Exports | 2.63 | 2.56 | -0.07 | Bearish |
| Lease/Plant/Pipe/Vehicle | 8.16 | 8.02 | -0.14 | Bearish |
| Total Demand | 109.30 | 106.17 | -3.12 | Bearish |
| Balancing Factor | -0.70 | +0.56 | +1.26 | — |
| Implied Daily Surplus | 9.91 | 11.48 | +1.57 | |
| Weekly Injection (Bcf) | +69.3 | +80.4 | +11.0 |
Note: Canadian pipeline imports are treated as a supply source; Canadian pipeline exports are treated as demand (gas leaving the domestic market). The Balancing Factor captures the residual between independently modeled supply and demand components and is reported below the totals — it is folded into the implied change but excluded from Total Supply and Total Demand.
Secondary Factors
Res/Com: Heating Load Still Dormant
Combined Res/Com demand eased -0.31 Bcf/d to 9.54 Bcf/d as the brief late-September heating stir faded and early-October temperatures hovered near seasonal norms. With HDDs still in the low single digits nationally, meaningful heating load has yet to arrive.
LNG Feedgas, Mexico Exports & Industrial
Total LNG feedgas slipped -0.09 Bcf/d to 18.60 Bcf/d, as disruptions at various facilities kept volumes off from their seasonal highs but roughly flat on the week. Pipeline exports to Mexico eased -0.34 Bcf/d to 6.98 Bcf/d as temperatures in Mexico moderated, while industrial demand was essentially flat at 22.27 Bcf/d (-0.04 Bcf/d). None of the secondary factors materially offset the continued slide in power burn.
Regional Power Burn
| Region | WE 9/25 (Bcf/d) | WE 10/02 (Bcf/d) | Δ WoW | LY (Bcf/d) | YoY Δ |
|---|---|---|---|---|---|
| East | 15.50 | 15.06 | -0.44 | 16.21 | -1.15 |
| Midwest | 5.00 | 4.75 | -0.25 | 4.86 | -0.11 |
| South Central | 14.00 | 12.66 | -1.34 | 11.67 | +0.99 |
| Mountain | 3.25 | 3.03 | -0.22 | 3.07 | -0.04 |
| Pacific | 2.58 | 2.70 | +0.12 | 2.17 | +0.53 |
| CONUS | 40.33 | 38.20 | -2.13 | 37.98 | +0.22 |
The remaining Gulf Coast heat broke this week, pulling South Central power burn down -1.34 Bcf/d and accounting for most of the national decline. The East and Midwest shed smaller amounts as their cooling load was already near baseline. Only the Pacific ticked higher. At the national level, CONUS power burn drifted back to roughly flat versus year-ago (+0.22 Bcf/d), with the South Central (+0.99) and Pacific (+0.53) running above last year while the East sat -1.15 Bcf/d below.
Outlook: Week Ending October 9
Early indications for the week ending October 9 point to an injection of 76 Bcf:
- Power burns down WoW: Keeping with the seasonal trend, modeled burns are off roughly 1.2 Bcf/d WoW as CDDs are also down slightly.
- Res/Com up WoW: Early-season Res/Com heating demand is now the pivotal variable. This week, a slight uptick in HDDs has induced a small increase in Res/Com demand (+1 Bcf/d), essentially offsetting the losses from the power sector.
- Production declines: Lower dry gas production is the primary culprit for the lower modeled injection for the week ending October 9, with CONUS levels down 0.5 Bcf/d WoW to 109.75. The northeast in particular has struggled for consistency as planned maintenance, force-majeures, and price related choke backs are keeping regional production around 34 Bcf/d, about 2 Bcf/d below month ago levels.
- LNG feedgas flat: Lower volumes at Freeport and Corpus Christi have kept the weekly totals flat, offsetting the recoveries at Sabine Pass and Calcasieu Pass from the week prior.
Methodology & Data Sources
Storage change is modeled as Total Supply (Dry Gas Production + Canadian Pipeline Imports + LNG Imports) minus Total Demand (all consumption sectors + LNG feedgas exports + pipeline exports), with the Balancing Factor added as a calibration residual, multiplied by seven days. The EIA storage week runs Saturday through Friday (the week ending October 2 covers Saturday September 26 through Friday October 2). Canadian pipeline imports are treated as a supply source supplementing domestic production; Canadian pipeline exports are treated as demand. The Balancing Factor (+0.56 Bcf/d this week) represents the residual between independently modeled supply and demand components and calibrates the injection estimate against EIA actuals.
Data sources: SynMax daily production model (hdl.daily_production), SynMax demand model (hdl.gas_demand, baseline scenarios), SynMax LNG feedgas model (hdl.lng_feed_gas), EIA Weekly Natural Gas Storage Report, NOAA GFS/HRRR weather data.
Disclaimer: This report is produced by SynMax Analytics for informational purposes only. Modeled figures are estimates and may differ from official EIA releases. Past model accuracy does not guarantee future performance.