Week Ending September 4, 2026
Weekly Storage and S/D Brief - Week Ending 9/11/2026
Week Ending September 11, 2026
SynMax Analytics | Published September 16, 2026
Headline
SynMax models a +44 Bcf injection for the week ending September 11, up 4 Bcf from the prior week's EIA-reported +40 Bcf build and the largest weekly injection of the past two months. In contrast to the prior week's supply-led acceleration, this week's loosening is demand-led: total demand fell -1.24 Bcf/d WoW to 113.80 Bcf/d as power burn retreated -1.57 Bcf/d to 46.02 Bcf/d with late-summer heat fading across the populous East and Midwest. Supply eased more modestly (-0.57 Bcf/d to 119.96 Bcf/d) as Canadian pipeline imports pulled back -0.80 Bcf/d to 7.14 Bcf/d while dry gas production edged up +0.23 Bcf/d to 112.83 Bcf/d. The daily surplus widened to 6.30 Bcf/d. If confirmed, working gas storage would stand at 3,298 Bcf, 125 Bcf below last year's pace but a comfortable +90 Bcf (+2.8%) above the five-year average.
Review the full analysis on the dashboard.
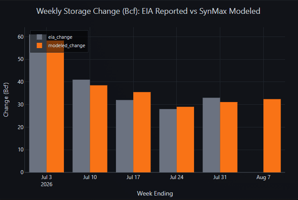
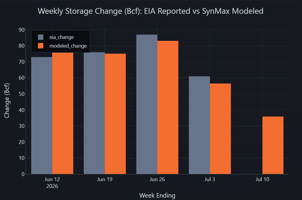
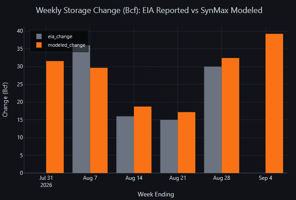
Model accuracy: Across the full scored window since July 3 (ten weeks, CONUS), the SynMax storage-number model has averaged a mean absolute error (MAE) of 3.9 Bcf and a small positive (over-injection) bias of +0.5 Bcf. Over the last five weeks the MAE runs 3.8 Bcf with a +2.8 Bcf high-side bias, reflecting the model's slightly firm read through the August lull.
| Week Ending | EIA (Bcf) | SynMax Model (Bcf) | Error |
|---|---|---|---|
| Jul 10 | +41 | +35.5 | -5.5 |
| Jul 17 | +32 | +33.4 | +1.4 |
| Jul 24 | +28 | +32.4 | +4.4 |
| Jul 31 | +33 | +33.2 | +0.2 |
| Aug 07 | +36 | +33.5 | -2.5 |
| Aug 14 | +16 | +24.4 | +8.4 |
| Aug 21 | +15 | +19.9 | +4.9 |
| Aug 28 | +30 | +30.5 | +0.5 |
| Sep 04 | +40 | +42.6 | +2.6 |
The accuracy table reflects the latest SynMax supply/demand models and may differ modestly from the official weekly storage-number call scored directly against EIA releases (which would have been based on the then-current models).
Primary Driver: Cooling Demand Fades as Late-Summer Heat Retreats
The defining feature of the week ending September 11 was a broad pullback in demand. Total demand fell -1.24 Bcf/d WoW to 113.80 Bcf/d, led by a -1.57 Bcf/d decline in CONUS electric power burn to 46.02 Bcf/d as national cooling degree days rolled over into the shoulder season. National population-weighted CDDs eased to 11.0 from 12.2 the prior week, with the cooldown concentrated in the northern tier.
The retreat was regionally uneven. Power burn fell hardest in the East (-1.97 Bcf/d to 17.90) and Midwest (-1.12 Bcf/d to 6.05) as Mid-Atlantic and Great Lakes heat broke, while the South Central actually firmed (+0.43 Bcf/d to 14.96) as Texas and the Gulf Coast held onto late-season warmth, and the Pacific rebounded (+1.04 Bcf/d to 3.36). Despite the WoW decline, national power burn still ran a robust +7.68 Bcf/d above the year-ago 38.34 Bcf/d, confirming demand strength remains predominantly weather-driven.
On the supply side, the picture eased only modestly. Total gross supply slipped -0.57 Bcf/d to 119.96 Bcf/d as Canadian pipeline imports gave back -0.80 Bcf/d to 7.14 Bcf/d after the prior week's rebound, partly offset by dry gas production edging up +0.23 Bcf/d to a fresh summer high of 112.83 Bcf/d. With demand falling more than twice as fast as supply, the weekly balance loosened and the injection climbed to a seasonal high.
Weather Context
National population-weighted CDDs averaged 11.0 for the week ending September 11, down from 12.2 the prior week but well above the year-ago 5.7:
- National cooling demand faded week-over-week as late-summer heat broke across the East and Midwest, pulling the national CDD count lower
- The cooldown was concentrated in the north: the East and Midwest led the retreat while the South Central held warm and the Pacific firmed
- Year-over-year, the +5.2 CDD gap (11.0 vs 5.7) continues to map onto the +7.68 Bcf/d YoY increase in power burn, keeping cooling load well ahead of last year despite the weekly fade
Supply & Demand Factor Changes (WoW)
| Factor | WE 9/04 (Bcf/d) | WE 9/11 (Bcf/d) | Δ WoW | Impact |
|---|---|---|---|---|
| SUPPLY | ||||
| Dry Gas Production | 112.60 | 112.83 | +0.23 | Bearish |
| Canada Pipeline Imports | 7.93 | 7.14 | -0.80 | Bullish |
| Total Gross Supply | 120.53 | 119.96 | -0.57 | Bullish |
| DEMAND | ||||
| Electric Power | 47.59 | 46.02 | -1.57 | Bearish |
| Industrial | 22.02 | 22.02 | +0.00 | Neutral |
| Res/Com | 8.13 | 8.27 | +0.14 | Bullish |
| LNG Feedgas (exports) | 19.11 | 19.28 | +0.17 | Bullish |
| Mexico Pipeline Exports | 7.27 | 7.12 | -0.15 | Bearish |
| Canada Pipeline Exports | 2.51 | 2.71 | +0.20 | Bullish |
| Lease/Plant/Pipe/Vehicle | 8.43 | 8.38 | -0.05 | Neutral |
| Total Demand | 115.04 | 113.80 | -1.24 | Bearish |
| Balancing Factor | -0.55 | -0.14 | +0.41 | — |
| Implied Daily Surplus | 6.04 | 6.30 | +0.27 | |
| Weekly Injection (Bcf) | +42.3 | +44.1 | +1.9 |
Note: Canadian pipeline imports are treated as a supply source; Canadian pipeline exports are treated as demand (gas leaving the domestic market). The Balancing Factor captures the residual between independently modeled supply and demand components and is reported below the totals — it is folded into the implied change but excluded from Total Supply and Total Demand.
Secondary Factors
Res/Com & LNG Feedgas: Modest Bullish Offsets
Combined Res/Com demand ticked up +0.14 Bcf/d to 8.27 Bcf/d as early-season heating load stirred in the northern tier, and total LNG feedgas firmed +0.17 Bcf/d to 19.28 Bcf/d as Gulf Coast terminals ran near capacity — a fresh weekly high. Both were bullish (tightening) factors, but their combined ~0.3 Bcf/d gain was far too small to offset the ~1.6 Bcf/d collapse in power burn.
Mexico Exports & Industrial
Pipeline exports to Mexico eased -0.15 Bcf/d to 7.12 Bcf/d as cross-border cooling demand softened. Industrial demand was flat at 22.02 Bcf/d, a non-factor in the weekly balance.
Regional Power Burn
| Region | WE 9/04 (Bcf/d) | WE 9/11 (Bcf/d) | Δ WoW | LY (Bcf/d) | YoY Δ |
|---|---|---|---|---|---|
| East | 19.87 | 17.90 | -1.97 | 16.38 | +1.52 |
| Midwest | 7.17 | 6.05 | -1.12 | 4.21 | +1.83 |
| South Central | 14.52 | 14.96 | +0.43 | 11.30 | +3.66 |
| Mountain | 3.70 | 3.76 | +0.06 | 3.72 | +0.04 |
| Pacific | 2.32 | 3.36 | +1.04 | 2.72 | +0.63 |
| CONUS | 47.59 | 46.02 | -1.57 | 38.34 | +7.68 |
The heat broke across the northern tier: the East and Midwest together shed more than 3 Bcf/d of power burn week-over-week, while the South Central held warm and the Pacific firmed. Every region still ran at or above year-ago levels, keeping the CONUS YoY gain at a robust +7.68 Bcf/d.
Outlook: Week Ending September 18
Early indications for the week ending September 18 point to an injection holding in the +50-60 Bcf range as seasonal cooling demand continues to fade into the shoulder season:
- Cooling demand fading: With the calendar deep into September, power burn are easing further toward the mid-to-low 40s Bcf/d as CDDs decline, widening the daily surplus
- Minor production disruption: Dry gas output was running near a summer-high 113 Bcf/d prior to this week’s mid-week dip from the Haynesville Basin
- LNG feedgas steady: Total throughput over 19 Bcf/d remains a persistent bullish offset, although a temporary decline from Cameron LNG (coinciding with the dip in Haynesville production) will likely result in lower total feedgas week-on-week.
Current Estimate: +57 Bcf
Methodology & Data Sources
Storage change is modeled as Total Supply (Dry Gas Production + Canadian Pipeline Imports + LNG Imports) minus Total Demand (all consumption sectors + LNG feedgas exports + pipeline exports), with the Balancing Factor added as a calibration residual, multiplied by seven days. The EIA storage week runs Saturday through Friday (the week ending September 11 covers Saturday September 5 through Friday September 11). Canadian pipeline imports are treated as a supply source supplementing domestic production; Canadian pipeline exports are treated as demand. The Balancing Factor (-0.14 Bcf/d this week) represents the residual between independently modeled supply and demand components and calibrates the injection estimate against EIA actuals.
Data sources: SynMax daily production model (hdl.daily_production), SynMax demand model (hdl.gas_demand, baseline scenarios), SynMax LNG feedgas model (hdl.lng_feed_gas), EIA Weekly Natural Gas Storage Report, NOAA GFS/HRRR weather data.
Disclaimer: This report is produced by SynMax Analytics for informational purposes only. Modeled figures are estimates and may differ from official EIA releases. Past model accuracy does not guarantee future performance.