Week Ending August 28, 2026
Weekly Storage and S/D Brief - Week Ending 10/30/2026
Week Ending October 30, 2026
SynMax Analytics | Published November 4, 2026
Headline
SynMax models a +79 Bcf injection for the week ending October 30, down 1 Bcf from the prior week's EIA-reported +80 Bcf build. If confirmed, working gas storage would stand at 3,803 Bcf. That is 102 Bcf below last year's level (3,905 Bcf) but roughly 58 Bcf (+1.5%) above the five-year average. The modeled build is well above last year's +33 Bcf for the same week and the five-year average of about +70 Bcf, so the year-on-year deficit would narrow sharply from 147 Bcf.
Review the full analysis on the dashboard.
Storage Summary
Last week the season's first real heating load absorbed the slack left by falling power burn. This week the two moved in opposite directions again, and the balance loosened modestly. Total demand eased 0.14 Bcf/d WoW to 106.68 Bcf/d. Res/Com demand fell 0.86 Bcf/d to 13.92 Bcf/d as the East and Midwest warmed, and a Freeport outage cut LNG feedgas 0.49 Bcf/d to 20.33 Bcf/d. Lower industrial demand (-0.56) and Mexico exports (-0.51) added to the loosening. A 1.99 Bcf/d rebound in CONUS power burn to 32.56 Bcf/d was the main offset. Total gross supply edged up 0.28 Bcf/d to 118.76 Bcf/d, with dry gas production steady at 111.58 Bcf/d.
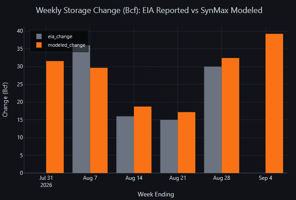
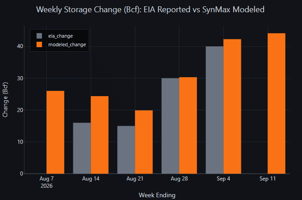
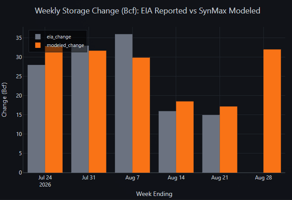
Model accuracy: Across the full scored window since July 3 (sixteen weeks, CONUS), the SynMax storage-number model has averaged a mean absolute error (MAE) of 4.0 Bcf, with a small positive (over-injection) bias of +0.9 Bcf. Over the last five weeks the MAE was 4.7 Bcf, with a +2.4 Bcf bias. Last week the model missed low for the first time in three weeks. The brief called +76 Bcf; the latest model run puts that week at +76.6 Bcf, against an EIA-reported +80 Bcf.
| Week Ending | EIA (Bcf) | SynMax Model (Bcf) | Error |
|---|---|---|---|
| Sep 25 | +64 | +69.4 | +5.4 |
| Oct 02 | +85 | +82.6 | -2.4 |
| Oct 09 | +67 | +72.8 | +5.8 |
| Oct 16 | +77 | +83.6 | +6.6 |
| Oct 23 | +80 | +76.6 | -3.4 |
The accuracy table reflects SynMax's latest supply/demand models. Modeled weekly values are recalculated as source data updates, so the resulting weekly storage may differ modestly from the official weekly storage-number call scored directly against EIA releases.
Primary Driver: Milder East Eases Heating Load as Power Burn Rebounds
Res/Com demand fell 0.86 Bcf/d WoW to 13.92 Bcf/d, giving back part of last week's jump. The decline came from the large eastern heating markets: the Midwest fell 0.85 Bcf/d to 2.95 Bcf/d and the East fell 0.62 Bcf/d to 5.70 Bcf/d as the October 17-18 cold gave way to milder air. The West partly offset this, with Mountain (+0.42) and Pacific (+0.29) Res/Com rising as cold moved into those regions. Res/Com is now 5.44 Bcf/d below last year's 19.35 Bcf/d, when the same week was much colder.
Power burn moved the other way. CONUS electric power burn rebounded 1.99 Bcf/d to 32.56 Bcf/d, its first weekly gain since mid-August, and is back above year-ago levels (+0.62 Bcf/d). South Central (+1.02 Bcf/d) and the East (+0.93 Bcf/d) drove the increase as late-season warmth returned to Texas and the Gulf Coast. Industrial demand slipped 0.56 Bcf/d to 22.85 Bcf/d, reversing most of last week's gain.
On the supply side, dry gas production edged up 0.12 Bcf/d to 111.58 Bcf/d, 4.86 Bcf/d above year-ago levels. The Northeast added a further 0.32 Bcf/d to 35.77 Bcf/d, the West slipped 0.14 Bcf/d, and the Gulf held near 44.1 Bcf/d. Canadian pipeline imports firmed 0.17 Bcf/d to 7.18 Bcf/d.
Net, the daily surplus widened 0.28 Bcf/d to 11.22 Bcf/d, lifting the modeled injection to +78.5 Bcf from the +76.6 Bcf model value for the prior week (+80 Bcf EIA-reported).
Weather Context
National population-weighted HDDs averaged 6.8 for the week ending October 30, down from the prior week's 8.2 and well below the year-ago 11.6:
- Cooling degree days were little changed at 1.4 (from 1.3), and the national average temperature rose 1.5°F to 59.6°F, about 5°F warmer than the same week last year.
- The East and Midwest warmed. HDDs fell to 7.9 in the East (from 10.7) and 6.7 in the Midwest (from 10.2), which drove the Res/Com decline. South Central turned warmer again (CDD 4.2 vs 2.0, HDD 0.6 vs 3.3), which supported its power-burn rebound.
- The West turned colder. Mountain HDDs rose to 11.2 (from 6.5) and Pacific HDDs to 7.8 (from 5.4), reversing last week's pattern. Because these markets are smaller, the western cold only partly offset the drop in eastern heating demand.
Supply & Demand Factor Changes (WoW)
| Factor | WE 10/23 (Bcf/d) | WE 10/30 (Bcf/d) | Δ WoW | Impact |
|---|---|---|---|---|
| SUPPLY | ||||
| Dry Gas Production | 111.46 | 111.58 | +0.12 | Bearish |
| Canada Pipeline Imports | 7.01 | 7.18 | +0.17 | Bearish |
| Total Gross Supply | 118.48 | 118.76 | +0.28 | Bearish |
| DEMAND | ||||
| Electric Power | 30.57 | 32.56 | +1.99 | Bullish |
| Industrial | 23.41 | 22.85 | -0.56 | Bearish |
| Res/Com | 14.78 | 13.92 | -0.86 | Bearish |
| LNG Feedgas (exports) | 20.82 | 20.33 | -0.49 | Bearish |
| Mexico Pipeline Exports | 6.77 | 6.26 | -0.51 | Bearish |
| Canada Pipeline Exports | 2.42 | 2.69 | +0.26 | Bullish |
| Lease/Plant/Pipe/Vehicle | 8.04 | 8.07 | +0.03 | Bullish |
| Total Demand | 106.82 | 106.68 | -0.14 | Bearish |
| Balancing Factor | +0.72 | +0.86 | +0.14 | — |
| Implied Daily Surplus | 10.94 | 11.22 | +0.28 | |
| Weekly Injection (Bcf) | +76.6 | +78.5 | +2.0 |
Note: Canadian pipeline imports are treated as a supply source; Canadian pipeline exports are treated as demand (gas leaving the domestic market). The Balancing Factor captures the residual between independently modeled supply and demand components and is reported below the totals. It is folded into the implied change but excluded from Total Supply and Total Demand. Prior-week values reflect the latest model run and may differ slightly from last week's brief.
Secondary Factors
LNG Feedgas: Freeport Outage Pulls Exports Off Their Highs
Total LNG feedgas fell 0.49 Bcf/d to 20.33 Bcf/d, though it still ran 2.11 Bcf/d above the year-ago level of 18.22 Bcf/d. The decline came entirely from Freeport, which dropped 0.73 Bcf/d to 1.52 Bcf/d for the week. Freeport flows fell to near zero (0.03 Bcf/d) on October 26 and recovered only gradually, to about 1.7 Bcf/d by October 30. Elsewhere, flows were firm. Corpus Christi added 0.13 Bcf/d to 3.68 Bcf/d and peaked at 3.91 Bcf/d on October 27, near its highest daily level since at least January 2024. Cameron rose 0.11 Bcf/d to 2.25 Bcf/d, and Calcasieu Pass rose 0.06 Bcf/d to 1.71 Bcf/d. Golden Pass averaged 0.74 Bcf/d and set a new daily high of 0.85 Bcf/d on October 30, followed by 0.86 Bcf/d on October 31, as its ramp continued.
Industrial, Mexico Exports & Canadian Flows
Industrial demand fell 0.56 Bcf/d to 22.85 Bcf/d, now 0.39 Bcf/d below last year's 23.24 Bcf/d. Pipeline exports to Mexico fell a further 0.51 Bcf/d to 6.26 Bcf/d as their seasonal autumn decline continued. Canadian pipeline imports firmed 0.17 Bcf/d and exports to Canada rose 0.26 Bcf/d, a small net outflow. Together, industrial demand and Mexico exports took about 1.1 Bcf/d out of demand. That was the largest bearish contribution on the week after Res/Com.
Regional Power Burn
| Region | WE 10/23 (Bcf/d) | WE 10/30 (Bcf/d) | Δ WoW | LY (Bcf/d) | YoY Δ |
|---|---|---|---|---|---|
| East | 12.43 | 13.35 | +0.93 | 14.03 | -0.68 |
| Midwest | 3.85 | 4.15 | +0.31 | 3.47 | +0.69 |
| South Central | 8.75 | 9.77 | +1.02 | 9.45 | +0.31 |
| Mountain | 2.74 | 2.75 | +0.01 | 2.75 | 0.00 |
| Pacific | 2.81 | 2.54 | -0.27 | 2.24 | +0.30 |
| CONUS | 30.57 | 32.56 | +1.99 | 31.94 | +0.62 |
Power burn rose in most regions as the cold front retreated. South Central (+1.02) and the East (+0.93) accounted for almost all of the gain, and the Midwest added 0.31 Bcf/d. The Pacific was the only region to fall (-0.27), consistent with cooler western weather. CONUS power burn is back above year-ago levels (+0.62 Bcf/d) after one week below. The Midwest (+0.69) and South Central (+0.31) more than offset an East still running 0.68 Bcf/d below last year.
Outlook: Week Ending November 6
Early data for the week ending November 6 (five of seven days, through November 4) point to a build of about +65 Bcf, down about 14 Bcf from this week as production has dropped sharply.
- Supply down: Dry gas production is averaging about 109.4 Bcf/d week-to-date, down about 2.2 Bcf/d, with daily output near 108 Bcf/d on November 3-4. The latest days may be revised as production data fills in. Canadian pipeline imports are higher at about 7.9 Bcf/d (+0.7 Bcf/d).
- Power burn eases: Power burn is averaging about 32.0 Bcf/d week-to-date (-0.6 Bcf/d), down from its October 31 peak of 34.6 Bcf/d.
- Res/Com little changed: Res/Com demand is averaging about 14.1 Bcf/d week-to-date (+0.2 Bcf/d). CONUS HDDs rose to about 8 over the October 31-November 1 weekend, then fell back to about 5 by November 3.
- LNG feedgas near 20.1 Bcf/d: Renewed Freeport weakness on November 1-3 keeps total feedgas slightly below this week's average. Initial nominations show Freeport partially recovering to about 1.7 Bcf/d for November 4.
- Weather ahead: The latest forecast holds CONUS HDDs near 5-6 through November 5, then steps them up to about 11-12 from November 7 and about 14-15 by November 12-13. That would be the first sustained winter-type cold of the season, and the transition to net withdrawals would follow in mid-November.
Early read: ~+65 Bcf based on week-to-date fundamentals. That compares with a +45 Bcf build in the same week last year and a five-year average of about +40 Bcf. The year-on-year storage deficit would narrow further, to roughly 66 Bcf.
Methodology & Data Sources
Storage change is modeled as Total Supply (Dry Gas Production + Canadian Pipeline Imports + LNG Imports) minus Total Demand (all consumption sectors + LNG feedgas exports + pipeline exports), net of the Balancing Factor calibration residual, multiplied by seven days. The EIA storage week runs Saturday through Friday; the week ending October 30 covers Saturday, October 24 through Friday, October 30. Canadian pipeline imports are treated as a supply source supplementing domestic production, and Canadian pipeline exports are treated as demand. The Balancing Factor (+0.86 Bcf/d this week) is the residual between independently modeled supply and demand components and calibrates the injection estimate against EIA actuals.
Data sources: SynMax daily production model (hdl.daily_production), SynMax demand model (hdl.gas_demand, baseline scenarios), SynMax LNG feedgas model (hdl.lng_feed_gas), EIA Weekly Natural Gas Storage Report (hdl.eia_storage_final), NOAA GFS/HRRR weather data.
Disclaimer: This report is produced by SynMax Analytics for informational purposes only. Modeled figures are estimates and may differ from official EIA releases. Past model accuracy does not guarantee future performance.