Week Ending October 16, 2026
Weekly Storage and S/D Brief - Week Ending 11/13/2026
Week Ending November 13, 2026
SynMax Analytics | Published November 18, 2026
Headline
SynMax models a +24 Bcf injection for the week ending November 13, down 37 Bcf from the prior week's EIA-reported +61 Bcf build. If confirmed, working gas storage would stand at 3,886 Bcf, or 50 Bcf below last year's level (3,936 Bcf) and 86 Bcf (+2.3%) above the five-year average (about 3,800 Bcf). The modeled build compares with a 14 Bcf withdrawal in the same week last year and a five-year average build of about +16 Bcf.
Storage Summary
Last week a production pullback tightened the balance. This week, heating demand took over. Res/Com demand jumped 5.62 Bcf/d WoW to 20.32 Bcf/d as the first sustained cold of the season reached the East and Midwest, and LNG feedgas rose 1.17 Bcf/d to 21.37 Bcf/d as Freeport returned to full rates. Industrial demand (+0.98) and power burn (+0.31) also rose, lifting total demand 8.46 Bcf/d to 116.27 Bcf/d. Supply recovered only part of that. Canadian imports rose a further 0.85 Bcf/d to 8.88 Bcf/d and dry gas production edged up 0.25 Bcf/d to 109.75 Bcf/d, for a total gross supply gain of 1.12 Bcf/d to 118.68 Bcf/d. The Balancing Factor swung negative (-1.07 vs +0.51 Bcf/d), offsetting part of the tightening. The implied daily surplus fell 5.75 Bcf/d to 3.49 Bcf/d.
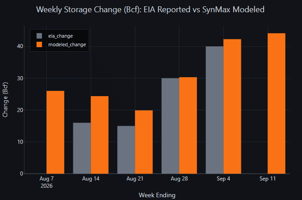
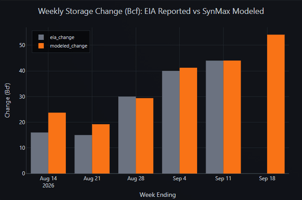
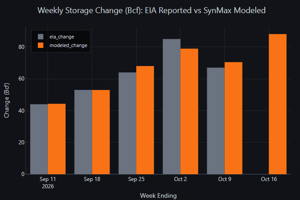
Model accuracy: Across the full scoring window since July 3 (nineteen weeks, CONUS), the SynMax storage-number model has averaged a mean absolute error (MAE) of 3.7 Bcf, with a small bias of +0.7 Bcf. Over the last five weeks the MAE was 3.8 Bcf, with a +2.0 Bcf bias.
| Week Ending | EIA (Bcf) | SynMax Model (Bcf) | Error |
|---|---|---|---|
| Oct 09 | +67 | +71.5 | +4.5 |
| Oct 16 | +77 | +83.4 | +6.4 |
| Oct 23 | +80 | +75.9 | -4.1 |
| Oct 30 | +77 | +76.6 | -0.4 |
| Nov 06 | +61 | +64.7 | +3.7 |
The accuracy table reflects SynMax's latest supply/demand models. Modeled weekly values are recalculated as source data updates, so the resulting weekly storage may differ modestly from the official weekly storage-number call scored directly against EIA releases.
Primary Driver: Heating Demand Arrives
Res/Com demand rose 5.62 Bcf/d to 20.32 Bcf/d, the largest weekly gain of the season, though it is still 6.38 Bcf/d below last year's 26.70 Bcf/d, when the same week was colder. The week opened cold, with Res/Com at 21.01 Bcf/d on November 7. It eased to 17.11 Bcf/d during a milder November 10-11 stretch, then surged to 27.01 Bcf/d on November 13 as a stronger cold front arrived. The Midwest (+2.93 Bcf/d) and East (+2.61 Bcf/d) drove nearly all of the gain, with South Central adding 0.46 Bcf/d. Mountain (-0.04) and Pacific (-0.32) eased as the West warmed.
The daily balance turned within the week. The implied daily surplus ran between 4.2 and 7.1 Bcf/d over November 7-11, narrowed to 1.3 Bcf/d on November 12 and flipped to a net withdrawal of about 4.9 Bcf/d on November 13, the first daily withdrawal of the season.
Other demand also firmed. LNG feedgas rose 1.17 Bcf/d (see below), industrial demand rose 0.98 Bcf/d to 23.94 Bcf/d, and CONUS power burn added 0.31 Bcf/d to 33.33 Bcf/d, now 2.57 Bcf/d above year-ago levels.
Supply offset only a small part of the demand gain. Dry gas production edged up 0.25 Bcf/d to 109.75 Bcf/d, 1.57 Bcf/d above last year's 108.18 Bcf/d. The Northeast (+0.45) and Gulf/TX/LA (+0.32) recovered part of last week's losses, while the West fell 0.48 Bcf/d. Canadian pipeline imports rose 0.85 Bcf/d to 8.88 Bcf/d, their highest weekly level in at least six weeks.
Net, the daily surplus narrowed 5.75 Bcf/d to 3.49 Bcf/d, cutting the modeled injection to +24.4 Bcf from the +64.7 Bcf model value for the prior week (+61 Bcf EIA-reported).
Weather Context
National population-weighted HDDs averaged 11.0 for the week ending November 13, up from 6.9 the prior week but still below the year-ago 14.7:
- The national average temperature fell 4.8°F to 54.9°F, still about 3.7°F warmer than the same week last year. CONUS HDDs ran 8-11 over November 7-12, then jumped to 16.9 on November 13 and 19.6 on November 14.
- The Midwest turned sharply colder. HDDs more than doubled to 18.3 (from 8.6) and the average temperature fell nearly 10°F to 46.7°F.
- The East also cooled. HDDs rose to 11.8 (from 5.7) and the average temperature fell 7°F to 54.4°F. Cooling degree days fell to 1.2 (from 2.1).
- South Central cooled (HDD 5.0 vs 1.6; CDD 0.9 vs 4.4), adding modest heating load.
- The West warmed. HDDs fell to 11.9 in Mountain (from 13.7) and 5.4 in Pacific (from 9.2).
Supply & Demand Factor Changes (WoW)
| Factor | WE 11/6 (Bcf/d) | WE 11/13 (Bcf/d) | Δ WoW | Impact |
|---|---|---|---|---|
| SUPPLY | ||||
| Dry Gas Production | 109.50 | 109.75 | +0.25 | Bearish |
| Canada Pipeline Imports | 8.03 | 8.88 | +0.85 | Bearish |
| LNG Imports | 0.03 | 0.05 | +0.02 | Bearish |
| Total Gross Supply | 117.56 | 118.68 | +1.12 | Bearish |
| DEMAND | ||||
| Electric Power | 33.02 | 33.33 | +0.31 | Bullish |
| Industrial | 22.96 | 23.94 | +0.98 | Bullish |
| Res/Com | 14.70 | 20.32 | +5.62 | Bullish |
| LNG Feedgas (exports) | 20.20 | 21.37 | +1.17 | Bullish |
| Mexico Pipeline Exports | 6.23 | 6.41 | +0.18 | Bullish |
| Canada Pipeline Exports | 2.67 | 2.57 | -0.10 | Bearish |
| Lease/Plant/Pipe/Vehicle | 8.03 | 8.33 | +0.30 | Bullish |
| Total Demand | 107.81 | 116.27 | +8.46 | Bullish |
| Balancing Factor | +0.51 | -1.07 | -1.58 | — |
| Implied Daily Surplus | 9.24 | 3.49 | -5.75 | |
| Weekly Injection (Bcf) | +64.7 | +24.4 | -40.3 |
Note: Canadian pipeline imports are treated as a supply source; Canadian pipeline exports are treated as demand (gas leaving the domestic market). The Balancing Factor captures the residual between independently modeled supply and demand components and is reported below the totals. It is folded into the implied change but excluded from Total Supply and Total Demand. Prior-week values reflect the latest model run and may differ slightly from last week's brief.
Secondary Factors
LNG Feedgas: Freeport Back at Full Rates
Total LNG feedgas rose 1.17 Bcf/d to 21.37 Bcf/d, 1.46 Bcf/d above the year-ago level of 19.91 Bcf/d. Freeport drove almost all of the gain. After last week's disruptions, it held between 2.32 and 2.48 Bcf/d every day, averaging 2.39 Bcf/d (+1.04). Corpus Christi added 0.10 Bcf/d to 3.75 Bcf/d and Cameron added 0.07 Bcf/d to 2.31 Bcf/d. Sabine Pass eased 0.12 Bcf/d to 4.76 Bcf/d after dipping to 4.29 Bcf/d on November 10, then recovered to 5.16 Bcf/d on November 13. Plaquemines (4.32), Golden Pass (0.83) and Calcasieu Pass (1.78) were steady.
Industrial, Mexico Exports & Canadian Flows
Industrial demand rose 0.98 Bcf/d to 23.94 Bcf/d with the colder weather, though it remains 0.89 Bcf/d below last year's 24.83 Bcf/d. Pipeline exports to Mexico rose 0.18 Bcf/d to 6.41 Bcf/d, ending several weeks of seasonal decline. Canadian imports rose 0.85 Bcf/d to 8.88 Bcf/d while exports to Canada slipped 0.10 Bcf/d to 2.57 Bcf/d. Net Canadian imports rose to about 6.3 Bcf/d (+0.95), again the largest bearish contribution on the week.
Regional Power Burn
| Region | WE 11/6 (Bcf/d) | WE 11/13 (Bcf/d) | Δ WoW | LY (Bcf/d) | YoY Δ |
|---|---|---|---|---|---|
| East | 14.10 | 13.89 | -0.21 | 13.33 | +0.56 |
| Midwest | 4.07 | 4.39 | +0.32 | 3.79 | +0.60 |
| South Central | 9.86 | 10.07 | +0.21 | 8.64 | +1.43 |
| Mountain | 2.62 | 2.64 | +0.02 | 2.71 | -0.07 |
| Pacific | 2.38 | 2.33 | -0.05 | 2.29 | +0.04 |
| CONUS | 33.02 | 33.33 | +0.31 | 30.76 | +2.57 |
The Midwest (+0.32) and South Central (+0.21) drove the national gain as colder weather lifted heating-season power load. The East eased 0.21 Bcf/d as cooling load faded. Mountain and Pacific were little changed. CONUS power burn runs 2.57 Bcf/d above last year. South Central (+1.43) accounts for more than half of that gap, with the Midwest (+0.60) and East (+0.56) adding most of the rest. Daily CONUS power burn peaked at 35.24 Bcf/d on November 12.
Outlook: Week Ending November 20
Early data for the week ending November 20 (five of seven days, through November 18) point to a net withdrawal of 3 Bcf, the first weekly withdrawal of the season.
- Res/Com surges again: Res/Com demand is averaging about 26.9 Bcf/d week-to-date (+6.6 Bcf/d), peaking at 29.95 Bcf/d on November 14. CONUS HDDs averaged about 17.5 over November 14-17, up from 11.0 last week.
- Production rebounds: Dry gas production is averaging about 112.0 Bcf/d week-to-date (+2.3 Bcf/d), with daily output near 112.7-112.9 Bcf/d over November 14-16. Canadian pipeline imports are steady at about 9.1 Bcf/d.
- LNG feedgas steady: Total feedgas is averaging about 21.2 Bcf/d week-to-date. Golden Pass dipped to 0.19 Bcf/d on November 16 before recovering to 0.84 Bcf/d by November 18.
- Industrial and power: Industrial demand is up about 1.2 Bcf/d to 25.1 Bcf/d. Power burn is up about 0.7 Bcf/d to 34.0 Bcf/d.
- Weather ahead: The latest forecast moderates CONUS HDDs to about 12 on November 19-22. Colder weather then returns, with HDDs near 22-23 on November 24-25 and 16-18 into early December. Withdrawals look likely to grow into the Thanksgiving week.
Early read: ~-3 Bcf. That compares with a 12 Bcf withdrawal in the same week last year and a five-year average withdrawal of about 24 Bcf.
Methodology & Data Sources
Storage change is modeled as Total Supply (Dry Gas Production + Canadian Pipeline Imports + LNG Imports) minus Total Demand (all consumption sectors + LNG feedgas exports + pipeline exports), net of the Balancing Factor calibration residual, multiplied by seven days. The EIA storage week runs Saturday through Friday; the week ending November 13 covers Saturday, November 7 through Friday, November 13. Canadian pipeline imports are treated as a supply source supplementing domestic production, and Canadian pipeline exports are treated as demand. The Balancing Factor (-1.07 Bcf/d this week) is the residual between independently modeled supply and demand components and calibrates the injection estimate against EIA actuals.
Data sources: SynMax daily production model (hdl.daily_production), SynMax demand model (hdl.gas_demand, baseline scenarios), SynMax LNG feedgas model (hdl.lng_feed_gas), EIA Weekly Natural Gas Storage Report (hdl.eia_storage_final), NOAA GFS/HRRR weather data.
Disclaimer: This report is produced by SynMax Analytics for informational purposes only. Modeled figures are estimates and may differ from official EIA releases. Past model accuracy does not guarantee future performance.