We wanted to share our latest production update, covering our revised Long term Forecast for oil...
We wanted to share our latest production update, covering our revised Long term Forecast for oil and natural gas as well as general model updates. View the full update on the Energy Dashboard and tune into our Quarterly Production Webinar, this morning at 10am EST.
This quarter's update has two parts. In the near term, the natural gas production forecast is revised lower: Q4 2026 is revised lower by about 1.0 Bcf/d, driven by November shut-ins (choke backs) due to storage injection ratchets from the very warm first half of November at a time when storage levels are generally near full. From 2027-2028, the forecast is revised higher: 2027 is revised up about 0.65 Bcf/d and 2028 is revised up about 0.8 Bcf/d, led by the Permian, the Gulf of America and the smaller oily basins. The higher natural gas production effect from higher 2027-2028 oil prices more than offsets the lower natural gas production effect from lower natural gas prices for 2027-2028. Oil prices for 2027-2028 went up a lot more than natural gas prices went down for 2027-2028 from our last forecast in late August. We have also extended the forecast horizon through December 2029. Despite the higher revised natural gas production growth for 2027, 2027 production growth is still expected to be lower compared to many other vendor forecasts due to more muted 2027 guidance on oil production growth from Devon Energy (up 1-3% YOY) and ConocoPhillips (up single digits YOY) and low ($2.50 / MMBtu, break even for new Haynesville wells) Henry Hub pricing from March through May 2027.
Overall and Producer Commentary
The Q3 2026 earnings season kept two themes from last quarter and added a third.
1. Efficiency still beats activity. Producers keep getting more out of each rig and frac crew:
- Apache said the rig count needed to hold its Permian production flat has fallen from 8 to 6 in 2025, to 4.5 in 1H26 and to 4 in 2H26 (APA, CHRD, CRK, GPOR, MUR & NFG).
- Enterprise Products raised its Permian gas and NGL growth outlook to 34% from 2025 to 2030, up from 23% last quarter. It credits rising GORs, shallower declines and better completions, not more rigs or crews (AR, CNX, EPD & PTEN).
- Lateral lengths keep growing. Devon expects about 10% longer laterals in 2027, EOG is up 16% YoY in the Dorado, and Chord is now TILing 4-mile wells (Ascent, BKV, COP, DVN, EOG, MNR & TALO).
- Chevron is dropping from 3 rigs to 2 in the Bakken on efficiency gains (BP, CVX, WTI & XOM).
2. Private operators are adding activity while public operators hold back.
- Halliburton said private operators are adding rigs while public producers stay disciplined. Our data shows rigs rising and frac crews falling from Q2 to Q3 2026 (HAL). The company also noted that large public operators are in their 2027 budget cycles, and that "all it takes is one or two of these guys to put together a program and that changes things."
- Liberty described the frac market as "tight," up from "improved modestly" last quarter. It said Q3 rig additions imply demand for 15–18 more frac crews in 2027 (KMI & LBRT).
- Patterson-UTI expects about 104 U.S. rigs in Q4 2026 and more reactivations in Q1 2027.
- Nabors expects 75 Lower 48 rigs in Q4, up from 72.8 in Q3 (BKR, EQT, EXE, NBR, PDS & RRC).
3. Gas producers curtailed in Appalachia and the Haynesville. This quarter's new theme is price-driven curtailment:
- EQT produced 5.92 Bcf/d in Q3 against a 6.3 Bcf/d guidance midpoint, after 21 Bcfe of strategic curtailments (about 4% of its dry gas). It kept full-year guidance, which implies a higher Q4 2026 (EQT).
- Antero curtailed about 10 Bcfe in Q3 and expects 15–20 Bcfe in Q4, about 6.8% of its dry gas (AR).
- National Fuel's fiscal-2027 guidance of 1.144 Bcf/d includes October marketing curtailments and implies flat to slightly lower 2027 volumes.
- Mach expects its Oklahoma gas production to fall mid-single digits in 2027 and said gas drilling "is mostly finished until it sees some price recovery."
- Northeast producers as a group saw Q3 2026 natural gas production come in below the midpoint of guidance due to larger than expected curtailments. Q4 2026 guidance is also implying significant curtailments for October and November.
Expand Energy dropped from about 12 rigs to 10 and deferred turn-in-lines (TILs). Its COO said:
"As we've come into the fourth quarter, we've ended up reducing some of our activity. That activity reduction, moving from around 12 rigs down to 10, is indirect acknowledgment that the market is weakening. We pushed out about nine turn-in lines out of Q3. We're waiting on those still to think about the optimal time to bring them online." – Expand Energy
We expect much of this gas to come back as winter prices firm. Antero's CEO pointed to TILs waiting "until December months to turn it on instead of September or October."
Other notable items:
- EQT agreed to buy Range Resources (expected to close Q1 2027). The combined company would hold about 23% of Northeast production (EQT Buys Range Resources).
- Kinder Morgan took FID on the Permian Link (2.8 Bcf/d, Q3 2030) and the Southeast Connector (2.6 Bcf/d, phased from Q4 2030) (KMI & LBRT).
- Diamondback took a 7.5% stake in the Solitude pipeline (2 × 2.25 Bcf/d, 2029/2030). Energy Transfer still expects Hugh Brinson Phase 2 in Q1 2027 (CRGY, ET & FANG).
- Service-company 2027 outlooks call for mid-single-digit growth: Halliburton, and SLB, which now says "the cycle has started" while calling North America "low-growth" (SLB).
Natural Gas Forecast
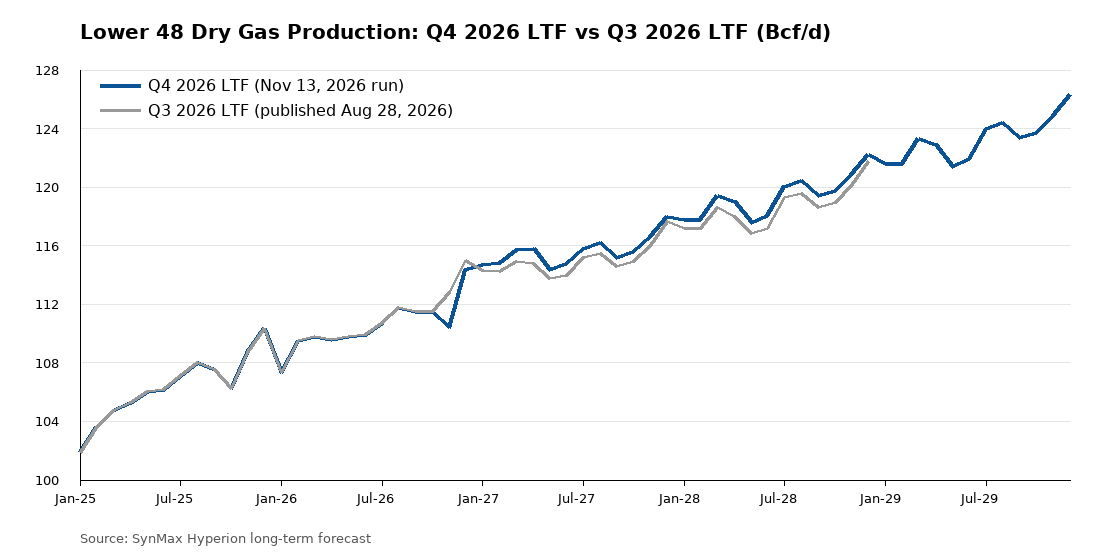
Here are the changes to the Lower 48 long-term forecast for natural gas production compared with the Q3 2026 LTF.
Q4 2026 is revised lower by 0.98 Bcf/d, to 112.1 Bcf/d. October is unchanged. November is revised down 2.37 Bcf/d, to 110.4 Bcf/d. The largest cuts are West Texas (-1.24 Bcf/d), Haynesville (-0.73 Bcf/d across LA and TX) and Appalachia (WV -0.30 and SW PA -0.28 Bcf/d). December recovers to 114.4 Bcf/d, 0.56 Bcf/d below the prior forecast, as curtailed and deferred volumes come back for winter. As a result, Lower 48 natural gas production for 2026 is now up 3.97% YoY, compared with 4.20% YoY in the prior forecast.
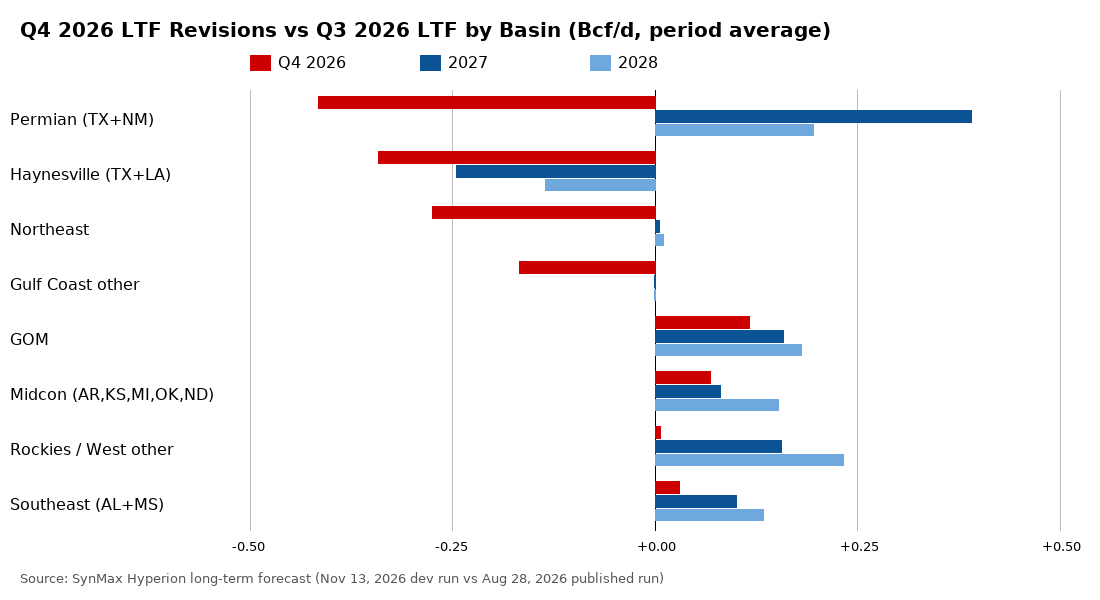
2027 is revised higher by 0.65 Bcf/d, to 115.6 Bcf/d (+4.62% YoY vs +3.81% previously). The largest upward revisions are:
- Permian: +0.39 Bcf/d, to 28.1 Bcf/d
- Gulf of America: +0.16 Bcf/d
- Southeast and Arkansas: about +0.25 Bcf/d combined
The Haynesville is revised lower by 0.25 Bcf/d, to 17.4 Bcf/d. The Northeast is unchanged at 36.4 Bcf/d, as curtailed volumes return but Q3 call commentary points to restrained 2027 programs. The December-to-December exit growth for 2027 is now +3.6 Bcf/d, compared with +2.7 Bcf/d previously. The forecast still dips in spring 2027, but from a higher level: March 2027 is 115.7 Bcf/d versus 114.9 Bcf/d previously.
2028 is revised higher by 0.77 Bcf/d, to 119.4 Bcf/d (+3.23% YoY vs +3.14% previously). 2029 is new to the forecast at 123.3 Bcf/d (+3.30% YoY).
| Lower 48 dry gas (Bcf/d) | Q3 2026 LTF | Q4 2026 LTF | Change | YoY (Q4 LTF) |
|---|---|---|---|---|
| 2025 (actual) | 106.32 | 106.32 | 0.00 | +4.11% |
| 2026 | 110.78 | 110.53 | -0.24 | +3.97% |
| Q4 2026 | 113.10 | 112.12 | -0.98 | – |
| 2027 | 115.00 | 115.64 | +0.65 | +4.62% |
| 2028 | 118.61 | 119.38 | +0.77 | +3.23% |
| 2029 | – | 123.31 | new | +3.30% |
| Basin (Bcf/d, annual avg) | 2027 Q3 LTF | 2027 Q4 LTF | 2028 Q3 LTF | 2028 Q4 LTF |
|---|---|---|---|---|
| Permian (TX + NM) | 27.74 | 28.13 | 29.88 | 30.08 |
| Haynesville (TX + LA) | 17.69 | 17.44 | 18.44 | 18.30 |
| Northeast | 36.39 | 36.39 | 36.86 | 36.87 |
| South TX | 6.89 | 6.89 | 7.08 | 7.08 |
| Oklahoma | 6.85 | 6.85 | 6.92 | 6.92 |
| Gulf of America | 1.69 | 1.85 | 1.69 | 1.87 |
Additionally, SynMax has updated the alignment of temperature data to gas days to better match the driving forces of demand to what is reported.
Oil Forecast
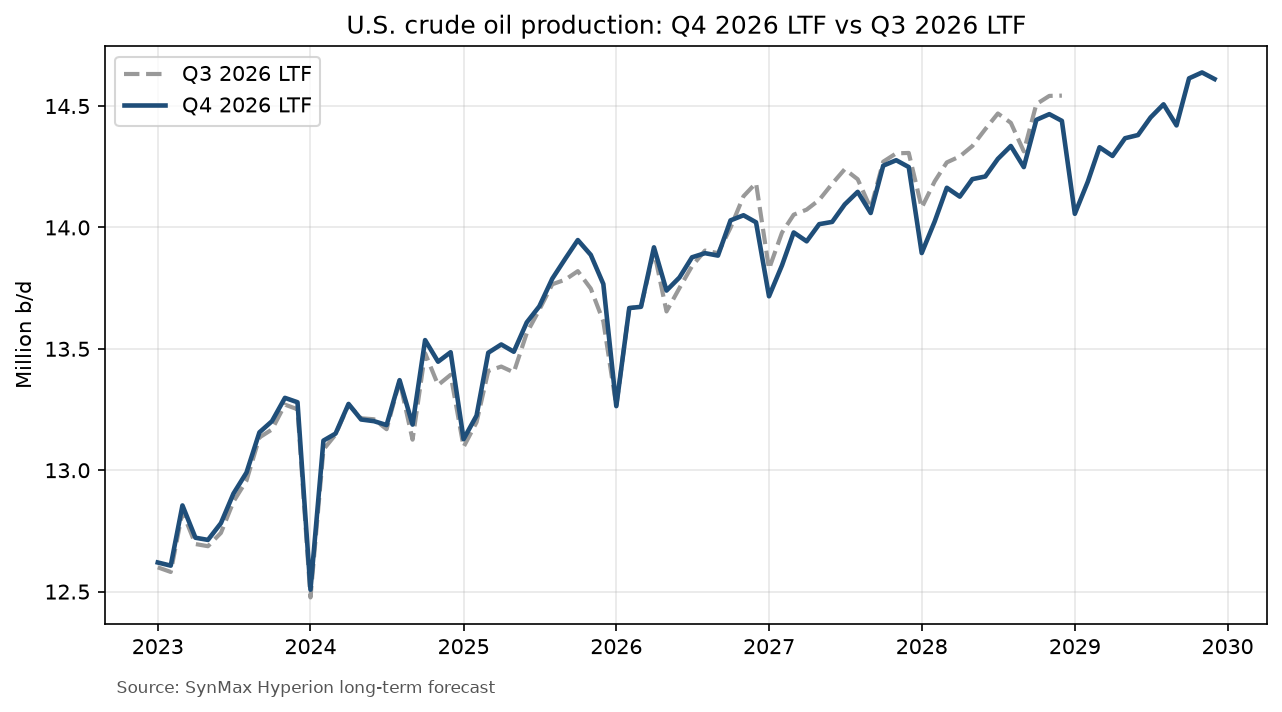
Here are the changes to the U.S. crude oil long-term forecast compared with the Q3 2026 LTF.
2026 is essentially unchanged at 13.82 mmbd (-4 mbd). Annual growth is now +202 mbd YoY, compared with +281 mbd YoY previously. Most of that difference comes from the 2025 baseline, not the outlook: 2025 actuals were revised up 75 mbd, including +140 mbd in Q4 2025, so the same 2026 level now represents less growth. Q4 2026 is revised lower by 70 mbd, to 14.03 mmbd. The forecast now reaches 14.02 mmbd in December 2026, 162 mbd below the prior forecast.
2027 is revised lower by 86 mbd, to 14.05 mmbd (+232 mbd YoY vs +314 mbd previously). 2028 is revised lower by 129 mbd, to 14.24 mmbd (+186 mbd YoY vs +229 mbd previously). 2029 is new to the forecast at 14.41 mmbd (+169 mbd YoY). Growth within 2027 is stronger, though: December-to-December growth is now +228 mbd, compared with +124 mbd previously. This is because the forecast starts the year from a lower December 2026 level.
Almost all of the revision is in the Permian. West Texas is down about 110 mbd from August 2026, and the gap widens to about 230 mbd in early 2027. As a result, Permian (TX + NM) growth in 2027 drops to +183 mbd, from +293 mbd previously. This is mostly a result of sideways results across the summer, undermining growth. We believe forward growth remains essentially the same, just on a lower base. The Gulf of America is the main offset, revised up about 90 mbd for 2027–2028, in line with Murphy and Talos raising guidance on minimal storm downtime. The Bakken, Eagle Ford, Rockies and Oklahoma are essentially unchanged. Virtually all growth still comes from the Permian, and most other basins remain flat to declining.
| U.S. crude oil (mbd) | Q3 2026 LTF | Q4 2026 LTF | Change | YoY (Q4 LTF) |
|---|---|---|---|---|
| 2025 (actual) | 13,541 | 13,616 | +75 | +392 |
| 2026 | 13,822 | 13,818 | -4 | +202 |
| Q4 2026 | 14,103 | 14,033 | -70 | – |
| 2027 | 14,136 | 14,050 | -86 | +232 |
| 2028 | 14,365 | 14,236 | -129 | +186 |
| 2029 | – | 14,405 | new | +169 |
| Basin (mbd, annual avg) | 2027 Q3 LTF | 2027 Q4 LTF | 2028 Q3 LTF | 2028 Q4 LTF |
|---|---|---|---|---|
| Permian (TX + NM) | 7,063 | 6,879 | 7,269 | 7,042 |
| Gulf of America | 1,969 | 2,059 | 1,969 | 2,059 |
| Bakken (ND + MT) | 1,230 | 1,229 | 1,234 | 1,233 |
| Eagle Ford / South TX | 1,155 | 1,155 | 1,166 | 1,166 |
| Rockies (CO, WY, UT, San Juan, NM ex-Permian) | 997 | 996 | 1,006 | 1,006 |
| Oklahoma | 404 | 402 | 406 | 406 |
Producer commentary relevant to the oil outlook:
- Apache raised 2026 U.S. oil guidance to 124 mbd.
- Chord raised 2026 oil volumes about 1%.
- Devon guided 2027 oil growth of 1–3%.
- ConocoPhillips guided low-single-digit 2027 growth.
- Murphy and Talos raised guidance on minimal storm downtime.
- Patterson-UTI said oil-basin activity is driving rig reactivations, especially in the Rockies and Permian.
- Diamondback said investors prefer Permian growth over growth in other basins.
Appendix: Updated Alignment Dates
[Analyst: refresh this table from the current Daily Production Model alignment dates before publishing.]
As usual, contact support@synmax.com with questions.