U.S. natural gas production is set for a moderate Q4 2026 seasonal ramp, estimated at +2.2 Bcf/d from current September month-to-date levels of ~112.7 Bcf/d to ~115.0 Bcf/d by December. This is below the 3-year historical Q4 average surge of +2.6 Bcf/d.
Much of the recent frac crew jump is seasonal preparation for winter, not incremental growth. Only Haynesville shows incremental activity (+48% YoY) driven by APEX all-time highs in frac crews.
Key Factors
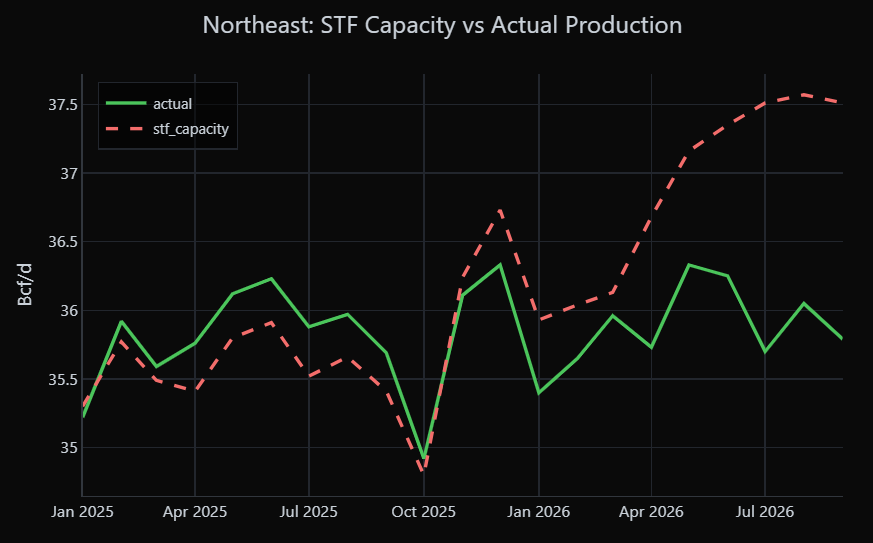
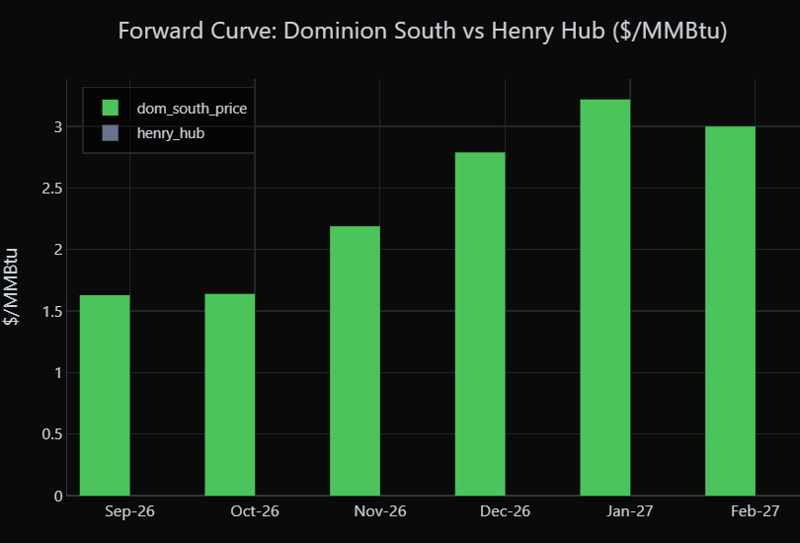
Blackcomb pipeline (Oct 1st expected online date) adds at least +0.3 Bcf/d Permian. APEX frac crews at record highs can increase Haynesville production by +0.5 Bcf/d. Lower 48 STF at 114.5 Bcf/d signals ~1.8 Bcf/d of production potential by December 2026. Northeast Short-Term Forecast) STF gap of 1.7 Bcf/d, due to Dominion South forward curve pricing incentivizes at least 0.7 Bcf/d for winter. There could very well be a 1.7 Bcf/d increase in Northeast production by December 2026 as compared to September 2026.
Risks & Caveats
Downside risks (could reduce surge below +2.0 Bcf/d):
- Freeze-offs: The 2022 precedent shows a Dec freeze-off can turn a +3 Bcf/d ramp into −1.6 Bcf/d. Early winter weather is the single largest risk factor.
- Pricing-driven curtailments: Henry Hub cash (spot) below $1.50/MMBtu triggers choke-backs. If spot prices remain suppressed deeper into Q4, curtailments could extend beyond the Northeast into Haynesville.
- Blackcomb delay: Pipeline commissioning slippage past Oct could defer ~0.3 Bcf/d of Permian capacity into 2027.
Upside risks (could push surge above +3.0 Bcf/d):
- Early cold snap: A Nov cold event could accelerate NE choke-back release, pushing NE closer to full +1.7 Bcf/d STF gap.
- Haynesville outperformance: APEX wells coming online faster than 3-month lag assumption.
- Higher winter pricing: If Henry Hub exceeds $4.00, it could pull forward curtailed volumes across all basins.
Read the full analysis on the dashboard.
As usual, contact support@synmax.com with questions.
